Elm Wealth Research

Thinking Outside the BOXX

February 27, 2024

Risk and Return

Thinking Outside the BOXX

By Victor Haghani and James White 1

There’s been a lot of excitement and reporting about a new ETF: the Alpha Architect 1-3 Month Box ETF (ticker BOXX), designed to give investors the return of short-term US Treasury Bills with the tax character of long-term capital gains.

Long-term capital gains are taxed at lower rates than interest income – 20% versus 37% for the top US federal tax rates. With short-term interest rates at about 5%, this 17% difference in tax rates provides 0.85% more annual after-tax return, and you can add another 0.07% if you use BOXX to defer your tax bill for 5 years. That’s pretty good, and worth paying attention to if you can get it.

Two excellent Bloomberg articles were published on Feb 22nd that do a terrific job explaining how BOXX achieves its tax “magic.” The first is by Zachary Mider, “T-Bills Without Tax Bills? and hours later came “Put the Money in the BOXX” by Matt Levine (and a few days later also by Matt there’s “Maybe Don’t Put the Money in the BOXX?”).

Since BOXX went live on December 22, 2022, its annualized return has been 0.09% higher than that of State Street’s SPDR Bloomberg 1-3 Month T-Bill ETF (ticker BIL). BOXX has a stated expense ratio of 0.395%, but currently charges 0.195% and has about $1 billion of assets, while BIL sports an expense ratio of 0.136%, has $31 billion of assets and has been around for 17 years.

However, past returns are not necessarily indicative of future performance, and we think it’s reasonable to expect that BOXX’s prospective post-tax, risk-adjusted return relative to BIL (or direct ownership of Treasury Bills) does not justify owning BOXX. Before diving in, we should qualify what follows by noting that we are not tax experts.

Let’s start with an analysis of the expected return of BOXX, and then we’ll move to assessing the relative risk of BOXX versus Treasury Bills. First, BOXX has a higher expense ratio than BIL. The stated long-term expense ratio of BOXX is 0.395% per annum,2 compared to 0.136% for BIL. At the long-term expense ratio, that takes 0.21%3 out of the 0.85% of tax savings, leaving 0.64% of net tax savings versus BIL.

Next, there’s the question of what rate of interest will be set by market participants who provide the other side of the BOXX options trades. Historically, as discussed in this article from the NY Fed, the implied interest rate in options boxes has averaged about 0.35% above T-Bills (from January 1996 through April 2023). While this historical positive spread may continue into the future, it is worthwhile to ask yourself how you would price those options if you were being asked to be the counterparty to BOXX’s trades?

Your selling of the options box-spreads generates cash – the cash that the BOXX ETF wants to invest – but at the same time, you’ll need to post collateral to the clearing exchange. You need to do this to give comfort to your counterparty – the Options Clearing Corporation (OCC) – that if you disappear with the cash, they won’t have a loss.

You’ll probably go out and buy a T-Bill of equal maturity to the expiration of the options you traded and post that as collateral to the OCC. For this to be worthwhile, you’ll need to price the options using an interest rate lower than the T-Bills you had to buy to post as collateral, so you can earn a spread.

How much of a spread you’ll want to earn is a difficult question to answer beyond saying “as much as I can get.” Perhaps one place we can look for an indication of what market participants charge for nearly risk-free trades is the much-discussed Treasury bond basis trade. A number of recent articles (here and here) indicate that traders demand an expected return of at least 0.5% per annum on assets.

This required profit margin by counterparties supplying the options trades to BOXX plus the higher expense ratio of BOXX leaves 0.24% of tax benefit for BOXX versus holding BIL. We should also make an allowance for higher transactions costs in all the trades BOXX needs to do, not only in all the various options trades, but also the trades with the Authorized Participants (APs) needed to clean out all the capital gains from the primary options trades used to invest the capital of the ETF.

For investors living in a state with an income and capital gains tax,4 state taxes must be considered as well. US T-Bills are exempt from state income tax but the capital gains from BOXX would not be. An investor in a state with a roughly 10% income tax would lose an additional 0.5% of the potential tax benefit of BOXX. Combined with the reduced benefits described above, this would render BOXX significantly less attractive than owning T-Bills through an ETF such as BIL, and even less so versus owning T-Bills directly.

Turning to the risk side, we see one primary risk, and a number of smaller secondary risks. The most notable risk is that the ETF is not investing in T-Bills, but rather it holds a position in options contracts in an omnibus account at its options broker, who in turn is exposed to the OCC, an entity with a AA credit rating. The OCC is an exchange, with a wide range of counterparties of varying credit quality. And we know that exchanges can get into trouble, despite intense regulatory oversight and the requirement that counterparties post collateral to mitigate credit exposure.5 For example, the near-insolvency of the London Metal Exchange in the wild nickel price runup in March 2022 illustrates that investing in an exchange is riskier than investing in US T-Bills. How much spread an investor should require for these credit risks is hard to quantify precisely, but we’d suggest something around 0.2% – 0.5% per annum as a reasonable estimate. Note that 0.35% per annum of spread represents a 50% probability of at least one default with a 50% loss every hundred years, which doesn’t feel to us like an overestimate of this risk.

Adding the cost of credit risk to all the other costs already noted gives us total costs greater than the 0.85% potential tax benefit. We might stop here, but a number of other risks are also worth mentioning. These include a negative tax ruling from the IRS on the BOXX mechanics (see Matt Levine’s aforementioned “Maybe Don’t Put the Money in the BOXX?” or Steven Rosenthal’s “Tax Gimmick in a BOXX”), higher transactions costs in executing its strategy, and wider spreads required by the ETF market makers (APs) due to the complexity of the structure and the lower liquidity of BOXX relative to larger and higher volume Treasury Bill ETFs. The latter two risks become especially salient as BOXX increases in size. A further risk for a BOXX investor with a long-term horizon is that if interest rates are lower in the future, the potential tax benefits of BOXX will be proportionately smaller.

Investors are generally attracted to owning US T-Bills as a safe and highly liquid place to keep some of their savings, to be instantly available for unexpected emergencies or investment opportunities. In order to get the tax benefit of investing in BOXX, a holding period of more than one year is needed, since the short-term capital gains rate is equal to the tax rate on interest income, at the highest marginal rates. This seems at odds with the primary rationale of holding T-Bills in the first place. If you have a 30% chance of needing to sell BOXX to raise cash within one year, that reduces the gross tax benefit by 0.25%.6

So, we’re not at present planning on using BOXX for our Elm Wealth clients, especially those who are subject to high rates of state taxation. However, what concerns us most about BOXX is the potential harm it may do to the whole ETF marketplace by creating a feeling that it is taking advantage of an ETF “loophole.”

We believe that the tax treatment of ETFs is more correct and equitable for investors than the tax treatment of traditional mutual funds, which can unfairly accelerate capital gains on long-term investors and create more capital gains than are actually realized by the mutual fund. We explained this in some detail in a note we wrote in 2015, “ETFs: Better Than Mutual Funds for Long Term Investors too?” More than 16 million US households benefit from the diversification, liquidity and fair tax treatment offered by ETFs, according to Investment Company Institute estimates. If the BOXX ETF grows so large and attracts so much attention that it precipitates a change in the rules governing ETF taxation, the result would be a tremendous and lamentable decrease in investor welfare. We truly hope our worries are misplaced.


  1. Thank you to Larry Hilibrand, Charles Wright, Dave Blob and Jon Seed for their helpful comments, and to Wes Gray and Larry Lempert for discussing specifics of their ETF with us. The opinions expressed in the article are not necessarily shared by those who gave us help. Nothing in this note should be taken as tax advice, or investment advice, or an offer or solicitation to invest. Past returns are not indicative of future performance.
  2. Although currently, the sponsor has a fee waiver in place until January 31, 2025 so that the expense ratio of the fund is 0.195%.
  3. Expressed in after-tax terms, using a 20% tax rate. We make this adjustment throughout this note where appropriate.
  4. Every state except Alaska, Florida, New Hampshire, Nevada, South Dakota, Tennessee, Texas, and Wyoming.
  5. At the end of 2022, the OCC had about $14 billion of assets supported by about $700 million of equity. BOXX’s $1.4 billion of assets represents over 10% of the OCC’s Clearing Fund Deposits as of end of 2022. See here
  6. An exception to this analysis is an investor for whom capital gains are effectively tax-free because he has capital loss carryforwards so large that they will never be fully used.
Read More

Elm in Bloomberg Magazine: The Most Costly Investment Mistake You Can Make Is Easy to Avoid

February 16, 2024

Risk and Return

Elm in Bloomberg Magazine: The Most Costly Investment Mistake You Can Make Is Easy to Avoid

By Victor Haghani and James White 1

There are a number of ways an investment can go south, but getting the size of a trade wrong can convert even a good trade into a bad bet. That’s the subject of our new article, “The Big Investment Mistake,” published in this month’s Bloomberg magazine.

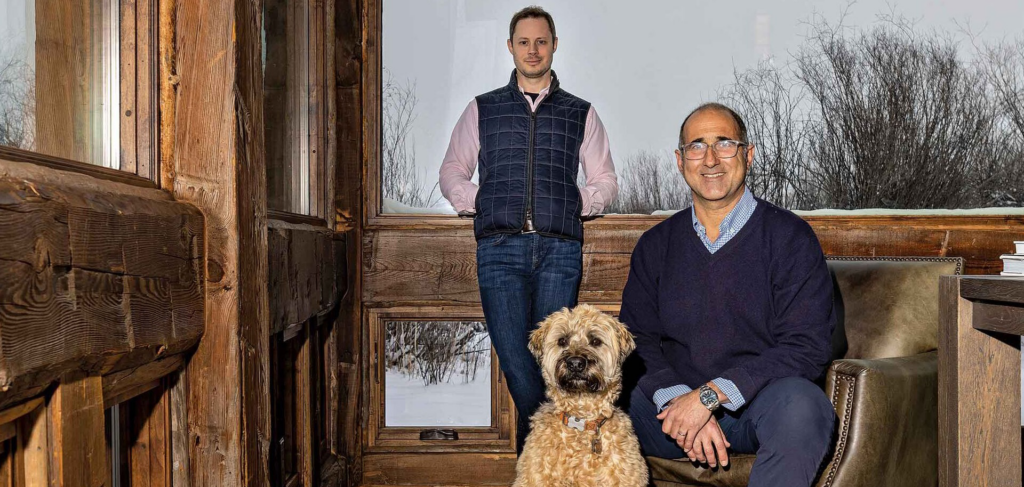
I hope you enjoy the article, but at the very least, you can see a gorgeous picture of Elm’s own Chief Happiness Officer – Milo, the soft-coated Wheaten terrier!

If you want to take a deeper dive into these topics, grab yourself a copy of our book, The Missing Billionaires: A Guide to Better Financial Decisions (named to The Economist’s Best Books of 2023 list).

The Missing Billionaires was included on the list for “The Best Books of 2023, as chosen by The Economist”, listed on 12/1/2023 for the time frame of calendar year 2023. This list is not based on any specific, publicly available criteria, it was compiled using The Economist’s own internal criteria and was based solely on the entity’s own thoughts and opinions. Neither Elm Wealth nor the book’s authors provided any form of compensation to be included on the list.


  1. This not is not an offer or solicitation to invest, nor should this be construed in any way as tax advice. Past returns are not indicative of future performance.
Read More

Sharpe’s Arithmetic and the Risk Matters Hypothesis

December 1, 2023

Featured Insights

Sharpe’s Arithmetic and the Risk Matters Hypothesis

By Victor Haghani, Vladimir Ragulin and James White 1

In Lake Wobegon, all the women are strong, all the men are good-looking, and all the children are above average.
  – Garrison Keillor

In 1991, William Sharpe made perhaps the strongest argument to date for market capitalization-weighted index investing in a three page article titled, “The Arithmetic of Active Investing”:

If “active” and “passive” management styles are defined in sensible ways, it must be the case that

(1) before costs, the return on the average actively-managed dollar will equal the return on the average passively-managed dollar and

(2) after costs, the return on the average actively-managed dollar will be less than the return on the average passively-managed dollar

These assertions will hold for any time period. Moreover, they depend only on the laws of addition, subtraction, multiplication and division. Nothing else is required.

The key insight of this idea is that, if we add all non-market capitalization-weighted portfolios together into one big portfolio, it must be identical to the market capitalization-weighted portfolio, i.e. the “market portfolio.” While the practical implications of Sharpe’s Arithmetic have been debated, its logic has been broadly accepted, and many see it as being one of the main drivers of the massive growth of index investing over the past three decades.2

Sharpe’s seminal paper landed a body blow on the stock-picking industry. Perhaps he felt his argument packed more than enough punch to make investors rethink their stance on stock-picking – but whatever his reasons, he stopped short of laying out a corollary to his “Arithmetic of Active Management”, which is just as powerful an indictment.

The corollary requires a bit more explanation than his main argument, but it is almost as simple and rests on the same basic insight laid out in his 1991 paper, that all active portfolios aggregate to the market portfolio:

(1) the average risk across all actively-managed portfolios of stocks will be greater than the risk of the market portfolio, and

(2) the average risk-adjusted excess return across all active portfolios will be less than the risk-adjusted excess return of the market portfolio, before taking account of fees and trading costs

We can see why the average risk across all active portfolios is greater than the risk of the market portfolio by seeing that every active portfolio can be expressed as holding the market portfolio plus an “active exposures” portfolio of longs and shorts in all the constituents, such that the market portfolio plus the active exposures portfolio equals the given active portfolio. Further, each active portfolio requires that there be someone(s) holding an active portfolio with the opposite active exposures, which we’ll call the mirror portfolio.

The average of the risk of any active portfolio and its mirror will be greater than the risk of the market portfolio. The key to seeing why is to notice that the two portfolios of active exposures have the same risk, but their correlations to the market portfolio will have opposite signs. As a result, when the portfolios are averaged together the correlation terms will cancel each other out, leaving just the extra tracking risk from the active exposures as an addition to the risk of the market portfolio. Since this holds for any active portfolio, it follows that averaging across any number of active portfolios gives the result that the average risk across all active portfolios must be greater than the risk of the market portfolio.

A little algebra shows us that the average of the risk of any arbitrary active portfolio and the risk of the mirror active portfolio must be greater than the risk of the market portfolio:3

Risk of the Active Portfolio = σm2 + σa2 + 2ρσmσa
Risk of the Mirror Portfolio = σm2 + σa2 – 2ρσmσa
Risk of the Market Portfolio = σm2

½((σm2 + σa2 + 2ρσmσa) + (σm2 + σa2 – 2ρσmσa)) > σm2
σm2 + σa2 > σm2
σa2 > 0

where σm is the standard deviation of returns of the market portfolio, σa is the standard deviation of returns of the portfolio of active exposures (i.e. tracking risk), and ρ is the correlation between the returns of the market portfolio and the returns of the portfolio of active exposures.

We cannot easily say how much higher the average risk of active portfolios will be versus the risk of the market portfolio, as it depends on the concentration of each active portfolio. However, we can get a sense for the magnitude by considering randomly constructed portfolios holding different numbers of stocks, such that in aggregate all the portfolios equal the market portfolio.

In the table below, we compare the risk of the market portfolio with the average risk of portfolios randomly constructed of 5, 25, and 100 stocks, selected so that they aggregate as closely as possible to the market portfolio.4 These concentrated portfolios have between 4% and 30% more risk than the market portfolio (see furthest right column). These active portfolios of N stocks are riskier than one might naively estimate by assuming that portfolio idiosyncratic risk decreases with √N1 . This is because 1) many of the idiosyncratic risks of individual stocks are correlated with each other (e.g. through being in the same industry sector or sharing factor exposures), and, 2) the uneven market capitalization weights result in greater concentration in portfolios than would arise from portfolios in which each stock had the same weight.

If, as was the case in the 1960s, the median number of stocks in an individual’s brokerage account was just two, the average riskiness of these highly concentrated portfolios would be 1.5x that of the market portfolio. A more recent 2005 study showed that stock investors with liquid assets over $1mm directly hold on average 15 stocks.5

Another viewpoint we can take is to compare the average risk of a set of non-market capitalization-weighted ETFs and mutual funds to the risk of the S&P 500 over the past 10 years. Even though these actively-managed funds hold about 200 stocks each, their average risk was 7% higher than the risk of the relevant market portfolio. In particular, it is very interesting to note that Vanguard’s growth and value funds – which each own over 200 stocks, and represent mirror active portfolios of each other – have an average risk that is 7% higher than the S&P 500.

You might say, what’s the big deal if the risk on a typical actively-managed portfolio is 10% higher than the risk of the market portfolio? Well, we think it is a big deal! Assuming it comprises most of the risky part of a portfolio, to be indifferent between the active portfolio and the market capitalization-indexed portfolio, you’d want them to have the same Sharpe ratio. This means the active portfolio would need to have 10% more expected return net of fees in excess of the safe asset than the market portfolio. If, for example, you think the market portfolio offers a 4% return in excess of the safe asset, then the active portfolio would need to offer 0.4% more, or a 4.4% excess return, just to be equally as attractive on a risk-adjusted basis.6

For years, investors and commentators have bemoaned the roughly 0.6% per annum difference between the average expense ratios on US actively-managed equity mutual funds and US equity index funds.7 We think they should be just as concerned, if not more so, by the extra cost of risk involved in holding concentrated portfolios in aggregate. This cost of risk of active management can easily be as large as or, in extreme cases of concentration, dwarf the extra fees that have garnered investor attention for so long.

Conclusion

Vanguard founder John Bogle was profoundly impacted by Sharpe’s Arithmetic, which he developed into his “Cost Matters Hypothesis” (CMH) presented in the same journal that published Sharpe’s Arithmetic 14 years earlier:8

Gross returns in the financial markets minus the costs of financial intermediation equal the net returns actually delivered to investors…To explain the dire odds that investors face in their quest to beat the market, however, we don’t need the EMH (Efficient Markets Hypothesis); we need only the CMH [Cost Matters Hypothesis]. No matter how efficient or inefficient markets may be, the returns earned by investors as a group must fall short of the market returns by precisely the amount of the aggregate costs they incur. It is the central fact of investing.

In the spirit of the late and great John Bogle, we would like to offer the “Risk Matters Hypothesis” (RMH), as an addition to the EMH and CMH in warning investors of the challenge they face in adding value through stock-picking:

The average risk-adjusted excess return across all active portfolios will be less than the risk-adjusted excess return of the market portfolio, before taking account of fees and trading costs.

As we discuss in more detail in our book, The Missing Billionaires: A Guide to Better Financial Decisions, it is natural that investors should and do require compensation for bearing risk. However, all too often we don’t adequately account for it in our investment decisions.

If there were no extra fees, taxes or other monetary costs associated with active management, Sharpe’s 1991 argument may not have been as influential as it has proved to be. In the past 30 years since Sharpe laid out his arithmetic, there has been a dramatic decrease in the fees charged by active stock managers, commissions for retail stock trades have gone to zero, and the inside bid-ask spread on equities has decreased. Taken together, these have reduced – but not eliminated – the importance of Sharpe’s original argument.

However, in the risk corollary to Sharpe’s Arithmetic described in this note, active investors are engaged in a negative sum activity even if there are no extra fees involved.9 Logic dictates that investors cannot in aggregate be rewarded for the extra risk they incur in owning concentrated stock portfolios.

Using Sharpe’s insightful observation that the portfolios of all active investors must equal the market portfolio and applying it in the dimension of risk, his original warning still rings true that active stock investors in aggregate need to overcome a substantial threshold of extra return in order to improve their welfare.


Further Reading and References


  1. This not is not an offer or solicitation to invest. Past returns are not indicative of future performance.
     

    We thank John Campbell, Jeffrey Rosenbluth and Mark Grinblatt for their help and encouragement. All errors are our own.

  2. For discussions of where Sharpe’s Arithmetic may not be a good model of reality, see Pedersen (2018), Chen et al. (2006), or Dick-Nielsen (2012) for the analysis of frictions in bond index funds.
  3. We recognize this is laid out informally. We hope to come back to this at a later date with a more rigorous treatment, including all assumptions needed. In the same spirit, this result also holds for the average standard deviation of returns, for -1 < ρ < 1, but the math is not as neat and tidy as it is for the average variances.
  4. We use the past 10 years of weekly return data, and current weights of the Bloomberg 500 US stock index. Our simulated investor portfolios hold stocks with market-cap weights, which is different from the standard calculation of diversification benefits which assumes equal weights, e.g. Malkiel (2023). Once the stock has been selected, we include it with the weight proportional to its market cap. This is because with the equal-weighted approach, it is not possible for the aggregated holdings to match the market weight of the mega-caps like AAPL by aggregating equal-weighted portfolios of more than 15 stocks, since even if each concentrated portfolio holds AAPL (which it wouldn’t), adding them together only gives a 6.7% AAPL weight ( = 1/15) for the aggregated portfolio – below the actual 7% weight. With our approach, an investor holds larger positions in the mega-caps, and therefore needs more stocks to achieve the same risk reduction vs. the standard equal-weighted approach.
  5. Stambaugh (2014).
  6. You may also ask, what’s the big deal about a 10% difference in Sharpe ratio, if you don’t expect a higher return on your actively-managed portfolio? The answer is that a 10% lower Sharpe ratio causes a 20% reduction in your risk-adjusted return, as we describe in The Missing Billionaires, Chapter 5, page 59.
  7. Average Equity and Bond Mutual Fund Expense Ratios Continue to Decline (2022).
  8. Bogle, J. 2015. “The Relentless Rules of Humble Arithmetic.” Financial Analysts Journal, 61 (6), 22-35.
  9. Ignoring some possible, though hard to observe or heavily weigh, risk transfer arguments.
Read More

A Closer Look at “Cut Your Losses Early; Let Your Profits Run”

August 7, 2023

Featured Insights

A Closer Look at “Cut Your Losses Early; Let Your Profits Run”

By Victor Haghani, Vladimir Ragulin and James White 1

“You know, some clichés are clichés because they are true.”
  – George Carlin

The first book that many new arrivals on the trading floors of banks and hedge funds are encouraged to read is Reminiscences of a Stock Operator by Edwin Lefevre (1923). The story highlights the importance of controlling one’s emotions in trading while being attuned to the herd mentality that often drives markets. The following two quotations reflect these twin themes of individual discipline and the pack-like movement of crowds:

“Cutting losses quickly is the foremost rule of speculating.”
“The big money is not in the buying or the selling, but in the waiting.”

For many successful speculators, “Cut your losses early; let your profits run” tops the list of advice they offer to the next generation of traders, as was the case with 12 out of the 14 renowned money men interviewed by Jack Schwager in Market Wizards: Interviews With Top Traders (1989).2 Here’s how one of the interviewees, Paul Tudor Jones, expressed it: “If I have positions going against me, I get right out; if they are going for me, I keep them.” This dictum is not lost on today’s most successful money managers, such as the Millennium, Balyasny and Exodus Point hedge fund groups, who put the tenet of cutting losses quickly at the very core of their investment and risk management policies.

Of course, this advice is far from universally accepted, and there are many situations where there is agreement that it’s not the right thing to do. Many people believe the qualities of perseverance, loyalty and determination are essential ingredients of success. The well-known author and psychologist Angela Duckworth wrote a popular book dedicated to this idea, aptly titled Grit. In it, she writes, “People who accomplished great things…often combined a passion for a single mission with an unswerving dedication to achieve that mission, whatever the obstacles and however long it might take.”

In the narrower sphere of investing, a number of financial economists – such as 2022 Nobel prize winner Phil Dybvig – have criticized the idea of a preset exit from an investment as being suboptimal at best and indefensibly irrational at worst. His 1988 paper “Inefficient Dynamic Portfolio Strategies or How to Throw Away a Million Dollars in the Stock Market” argues that strategies that cut risk to zero following losses are strictly suboptimal if asset prices follow random walks and investors exhibit smoothly decreasing marginal utility of wealth.3

However, most practitioners believe that there are times when markets don’t follow the well-behaved random walks which underlie many elegant formulas of modern finance. The rest of this note will explore two cases in the context of investing where the policy of cutting losses quickly and letting profits run (which we’ll abbreviate to CLE-LPR) can make sense. If you’re interested in the question of whether CLE-LPR makes sense in the broader context of other life decisions, read “Heads or Tails: The Impact of a Coin Toss on Major Life Decisions and Subsequent Happiness.” (Levitt, 2021), or watch Victor’s short TEDx talk: Quitting is for Losers Winners. (Haghani, 2017).

In the chart below, we see how a CLE-LPR strategy would have fared if applied to US stock market investing over roughly the past 100 years. It shows historical returns of investing in the S&P500 index with a CLE-LPR strategy versus a static weight (70% stocks/30% T-bills) portfolio of equal risk. For the dynamic strategy, we sell our S&P 500 long position and invest in T-Bills as soon as the trailing 12-month return drops below -5%, stay out of the market for at least three months, and reinstate the long as soon as the 12-month return is better than -5%.

This approach means losses are cut early, while a profitable position is held as long as it keeps going up. The CLE-LPR strategy generated a 1.4% higher annual return over the period with the same risk measured as standard deviation of daily returns, and roughly the same average exposure to the stock market of 70%.4 This translates into a 25% higher Sharpe Ratio for the dynamic strategy than for the static stock/T-bill portfolio (0.53 vs. 0.43).

Also, the Cut-Losses-Early-and-Let-Profits-Run strategy outperformed the static portfolio during the two worst market sell-offs in 1929-32 and 2007-09, when the static portfolio’s max drawdowns were 70% and 41% respectively, while the CLE-LPR’s largest drops during the same crises were 42% and 21%.

Why Does Cut-Losses-Early-and-Let-Profits-Run Work?

One way to answer this question might be to notice that this investment approach is very similar to momentum-based investing,5 which has been very successful over a wide range of asset markets and time periods. For example, in “Time Series Momentum” (2012), Moskowitz et al. found “… significant time series momentum in equity index, currency, commodity, and bond futures for each of the 58 liquid instruments we consider.”6 Over the period of our simulation, a momentum signal based on the past year of stock market performance would have lined up with the positioning from the CLE-LPR strategy 94% of the time.

Of course, pointing out that CLE-LPR is very similar to momentum investing doesn’t really answer the question, it just reformulates it into: “Why do momentum strategies work?” It’s hard to know for sure, but there are many theories to choose from. They range from underreaction to new information, to overreliance on recent returns in forming expectations of future returns (a.k.a “return chasing”), to slow recognition of regime shifts in markets, just to name a few. In most markets, positive momentum is usually associated with periods of lower risk, which in turn may encourage investors to want to own more of that asset, thus increasing the price.7 Whatever the reason, there is little doubt that momentum in asset prices has been present for a long time, across a wide range of traded assets.

Why Some Hedge Fund Managers Love CLE-LPR

Imagine you run a hedge fund and your job is to allocate capital to a set of traders. To keep things simple, let’s assume you’re managing just one trader, and he tells you that he can generate $2 of profit for every $1 of risk he takes on an annual basis.8 That is, he is telling you that the distribution of his trading PnL has a Sharpe Ratio of 2.

You feel that the biggest loss your investors will tolerate is about 10% in a given year, so you want to make sure there’s a very low probability that your Fund loses more than 10%. You’re considering two ways of managing your trader.

Under the first, you tell him that his risk, measured in annual standard deviation of returns, can be no higher than 10% of the Fund’s capital. If his trading has a Sharpe Ratio of 2, you reason that the probability of losing 10% at some point during the year is about 1.3%, which you feel is tolerable.

Under the second regime, you tell him that he should take risk in proportion to how far away he is from losing 10% of the Fund’s capital. To begin with, when he’s 10% away, he can take 10% risk. Later on, if he’s made 5% profits, and so he’s 15% away – he can take 15% risk. If he’s close to losing 10%, then he has to have cut his positions down close to zero. This pattern of position sizing is the embodiment of “cut your losses early and let your profits run.”9

Let’s compare the implications of these two ways of managing the trader’s risk-taking. Under both regimes, assuming the trader believes his trading has a Sharpe Ratio of 2, he will start off running risk equal to 10% of the Fund’s capital.10 The trader under the first system will keep his risk constant at 10% of the Fund’s capital as his PnL evolves, while the trader under the CLE-LPR regime will be dramatically increasing and decreasing his risk as his trading profit and loss fluctuates over time, in proportion to how far away he is from losing 10% of the Fund’s capital.

The chart below shows the probability distribution of outcomes for the Fund’s return under the two regimes, in both cases assuming the trader’s PnL has a Sharpe Ratio of 2. We believe everyone involved – you as the hedge fund manager, the trader who works for you, and your investors – will prefer the return pattern from the CLE-LPR regime to the return pattern arising from taking constant risk.

The CLE-LPR regime produces a higher expected net return (50% vs 18%),11 with only a slightly higher probability of loss (6% vs 2%) and a much higher expected fee for the hedge fund manager and trader to share (12.5% vs 4.5% of capital, assuming a 20% incentive fee). Perhaps the biggest advantage is that, if you are wrong about the skill of the trader and it turns out that his true trading Sharpe Ratio is 0, then under the constant risk regime, there’s a 1-in-3 chance of hitting -10% during the year, while the risk of a -10% return in the CLE-LPR regime remains zero, by construction.12 In addition to this being a very valuable protection for the hedge fund manager and the hedge fund investors, a trader who suspects he has little skill has a strong incentive to avoid working for a hedge fund that employs a tight CLE-LPR risk-management regime.13

Conclusion

Most people are naturally inclined to patiently, and painfully, stick with losing decisions for too long while cashing out of winning decisions too quickly. Indeed, this was an early finding in the field of behavioral economics, and was important enough to be given a name: the “Disposition Effect.”14 It is often the case that controlling our natural instincts can be rewarding. We suspect that much of the power of cutting losses quickly and letting profits run, at least when it comes to investing, lies in the difficulty of overcoming our propensity to do the exact opposite.


Further Reading and References

  • Baur, DG & Dimpfl, T. (2023). “Cut Your Losses and Let Your Profits Run.” Journal of Portfolio Management (forthcoming), SSRN.
  • Duckworth, A. (2017). Grit: Why Passion and Resilience are the Secrets to Success. Vermilion.
  • Dybvig, PH. (1988). “Inefficient Dynamic Portfolio Strategies or How to Throw Away a Million Dollars in the Stock Market.” The Review of Financial Studies.
  • Forsyth, PA, & Vetzal, KR. (2023). “Multi-period Mean Expected-Shortfall Strategies: ‘Cut Your Losses and Ride Your Gains’.” Applied Mathematical Finance, 29(5).
  • Geczy, C., & Samonov, M. (2017). “Two Centuries of Multi-Asset Momentum (Equities, Bonds, Currencies, Sectors and Stocks).” SSRN.com.
  • Haghani, V. (2017). Quitting is for Winners. TedX.
  • Haghani, V., & McBride, S. (2016). “Return Chasing Can be Hazardous to Your Wealth.” Elm Wealth.
  • Lefevre, E. (1923). Reminiscences of a Stock Operator: The Story of Jesse Livermore, Wall Street’s Legendary Investor. Cosimo Classics.
  • Levitt, SD. (2021). “Heads or Tails: The Impact of a Coin Toss on Major Life Decisions and Subsequent Happiness.” The Review of Economic Studies, 88(1), 378-405.
  • Moskowitz, T., Yao Hua Ooi, YH, & Pedersen, LH, (2012). Time series momentum.” Journal of Financial Economics, 104(2), 228-250.
  • Shefrin, H., & Statman, M. (1985). “The Disposition to Sell Winners Too Early and Ride Losers Too Long: Theory and Evidence.” Journal of Finance, 40(3), 777-790.
  • Stone, M., Michalow, D., & Beck, T. (2011 May). “Blind ambitions.” Institutional Investor Magazine.
  • Kaminski, K. & Lo, A. (2014). “When do stop-loss rules stop losses?” Journal of Financial Markets 18(C), 234-254.

  1. This not is not an offer or solicitation to invest. Past returns are not indicative of future performance.
     

    We thank Andy Morton and Rich Dewey for their valuable input.

  2. ChatGPT4 agrees: “One of the most popular sayings related to managing trading profit and loss is: ‘Cut your losses short and let your profits run.’ This phrase emphasizes the importance of having a well-defined exit strategy to limit losses when a trade goes against you and to allow winning trades to continue capturing profits.”
  3. A simple intuition for this result is that, in the absence of regime changes or private market forecasts, the optimal position is given by the well-known Merton Rule – and any deviation from it, via a stop-loss or another overlay, only results in the investor leaving money, or more accurately, ‘expected risk-adjusted return’ on the table.
  4. Ignoring transaction costs. The t-stat of the excess return is 1.3, which represents a confidence level of 90%.
  5. Time series momentum is a phenomenon where assets that have exhibited strong (poor) past performance over a certain time period, usually six months to one year, tend to continue performing well (poorly) in the near future.
  6. Also see: Geczy and Samonov,. (2017). “Two Centuries of Multi-Asset Momentum: (Equities, Bonds, Currencies, Commodities, Sectors and Stocks).”
  7. This explanation doesn’t fit so well in the case of momentum in bond prices. Bonds tend to be more volatile in a financial crisis, when bond price momentum tends to be positive.
  8. We’re making further idealistic assumptions that the return distribution of the trader is normally distributed and that trading takes place continuously with no transaction costs. We are also assuming the risk-free interest rate is 0, and the fund charges no management fee.
  9. This risk-taking approach would naturally arise if the trader were trying to maximize his Expected Utility, with a Constant Relative Risk Aversion Utility function taking his buffer capital as his wealth. With the numbers in this example, the implied coefficient of risk aversion would be 2, a typical value in the personal investing context.
  10. We’re also assuming his personal risk aversion is low enough that he’ll be happy using his full risk budget.
  11. This may seem like a strange and surprising result – in fact, we haven’t seen it written about before. Under the two regimes, the starting risk and hence position is the same, but over time the trading is different. There will be a larger expected position size under the CLE-LPR regime, and hence a higher expected gain.
  12. And with the assumption that the positions of the trader are perfectly liquid.
  13. The annual expected P&L of a strategy assuming optimal risk allocation is proportional to the square of the Sharpe Ratio since, from Merton’s analysis, a better trader is both comfortable with taking more risk and expects to earn a higher return on each unit of risk he takes. The formula is Expected P&L at Optimal Risk = Capital * SR2 / risk-aversion. With this rule of thumb, the hedge fund manager can select risk allocation parameters such that potential earnings for a high SR trader considering joining the fund just exceed compensation from alternative jobs.
  14. See Shefrin and Statman’s 1985 paper, “The Disposition to Sell Winners Too Early and Ride Losers Too Long: Theory and Evidence.”
Read More

John Y. Campbell on The Rational Reminder Podcast

June 21, 2023

Investing 101

John Y. Campbell on The Rational Reminder Podcast

It’s been a while since we last shared some thoughts on financial decision-making. The reason is that we’ve been busy finishing a book on that very topic, which should be in print by September – but we recently stumbled upon a terrific podcast interview of John Y. Campbell, a professor of finance at Harvard who has written two of our favorite books on finance and is one of the clearest communicators we know. We have learned a great deal from John over the years.

John touches on just about every important idea in investing and financial decision-making, from utility theory and risk aversion to the benefits and drawbacks of value investing. We hope you’ll listen through to the end, as we found the last few minutes particularly moving and memorable.

You can watch the video below:

You can also listen to the audio version via Spotify or Apple Podcasts, or read the full transcript on the Rational Reminder website.

Read More

Victor on the ‘What Happens Next’ podcast: “How Should I Invest My Money?”

March 30, 2023

In the News

Victor on the ‘What Happens Next’ podcast: “How Should I Invest My Money?”

Victor was recently a guest on his friend Larry Bernstein’s What Happens Next in 6 Minutes podcast, along with their dear friend and former colleague, Nobel Laureate Myron Scholes. They discussed their views of the essentials, or Golden Rules, of investing. You can listen to the podcast on Spotify or iTunes, or you can read the transcript of the podcast reproduced below. We hope you’ll enjoy the discussion.


Larry Bernstein: Welcome to What Happens Next. My name is Larry Bernstein.

What Happens Next is a podcast which covers economics, finance, politics, and sports. I give the speaker just six minutes to make his opening argument.

Today’s topic is Intelligent Investing.

Our speakers will be Victor Haghani, who is a former Salomon Brothers colleague of mine and one of the founders of Long-Term Capital Management. A decade ago, Victor founded a wealth advisor, Elm Wealth, as an extension of managing his family office.

I endorse Victor’s wealth management strategy that dynamically manages portfolios of low-cost ETFs focused on delivering attractive risk-adjusted, after-tax returns for clients. You will hear directly from Vic about these ideas and you can learn more from his website, ElmWealth.com.

Our second speaker is Myron Scholes, who won the Nobel Prize for his contributions to options theory, which is just a tiny fraction of his many contributions to finance. Myron will speak today about the importance of diversification both across assets and time. Myron was an early advocate of low-cost index funds and believes that you need to dynamically change your investment portfolio when market risk conditions change.

There is much to cover, so buckle up.

I make this podcast to learn, and I offer it free of charge. If you enjoy today’s podcast, please subscribe from our website for weekly emails so that you can continue to enjoy this content.

Ok, let us begin with Victor’s opening six-minute remarks.

Victor Haghani: My perfect portfolio is based on two core ideas. The first is the golden rule of investing. You can’t expect higher returns without taking more risk – return and risk are bound together – but you can get more risk without getting more return, which leads to an important corollary. You shouldn’t expect higher returns for risks that you can eliminate through diversification. The golden rule is enforced by the competitiveness and efficiency of markets. Everyone is looking for return without risk, the proverbial free lunch, and that makes it difficult to find, if at all. The second rule addresses the ‘how much’ question – it’s not enough to know what to invest in, but we also have to decide how much we want to put at risk in those investments. The answer is that we should choose the portfolio which gives us the highest expected risk-adjusted return, where the adjustment we make for risk reflects our own personal degree of risk aversion.

It follows from the second rule that the higher the expected return you can get for a given amount of risk, the more risk you should be willing to take. This second question of investing gets a lot less attention than it deserves, since it’s actually more critical to get right than the first question. Taking too much or too little risk can be much more damaging to your welfare, even if you make good choices of what to invest in.

I’m just finishing a book that mostly addresses this second question, with my partner in Elm Wealth, James White; it’s being published by Wiley and it will be in bookstores in about six months. People who agree on these two ideas and who have similar levels of risk aversion will wind up with similar portfolios – not identical, but close enough to call them the same for practical purposes.

The first rule dictates that your portfolio should be as diversified as possible, which makes low-cost, broad market ETFs the portfolio building blocks of choice. The second rule calls for changing your portfolio as the expected return and risk of assets change over time. It calls for dynamic asset allocation.

For example, if real interest rates go up 1% but equities don’t move at all, doesn’t it make sense all else equal to increase your exposure to bonds and decrease your exposure to equities? Not only is this the rational thing to do, but it also satisfies the need to be responsive and active, but in a disciplined and systematic way that keeps our cognitive biases at bay, stopping us from chasing whatever is hot and dumping whatever is not, usually at just the wrong times.

You’ll want to get your perfect portfolio at the lowest possible price, meaning you want to pay the lowest possible fees and you want it to be as tax-efficient as possible too, and it should take up as little of your precious time and attention as possible. This last point is very important to me, I don’t want my kids to feel that they have to spend a lot of time managing and monitoring their savings. I want them to see that, even though their father was an investment professional, I didn’t spend my time obsessing over investing and trying to beat the market. Isn’t that what financial freedom really is? And so, that’s how I think about the perfect portfolio. I was 45 years old by the time I truly accepted these ideas, first for my family and then for the clients of Elm Wealth, the wealth advisory firm I founded in 2011. If you want to learn more about these two rules and how they can be put into practice, visit me online at elmwealth.com.

LB: Myron, let’s get you into the conversation. Can you describe your role in the development of index funds and passive investing?

Myron Scholes: In 1968, I was graduating from the University of Chicago, and I was asked by Wells Fargo Bank to apply the Markowitz portfolio theory model to allocating money.

I suggested that, instead of an active manager, the future was passive investing in index funds. From there, it took four years before Wells Fargo could get its first client. But everyone thought the idea of indexing was crazy. No one had done passive investing. That was completely foreign to anyone’s thinking at the time. Now, it represents over 30% of the market, and many other investors who claim to be active really hug the index and do not deviate very far from the index at all. It may be over 50% of investing if you really take the active component out of many portfolio manager’s decisions.

LB: What should be the role of index funds in an investor’s portfolio?

MS: It should be the core of anyone’s investment strategy. That should be the starting point and a particularly wonderful way to invest.

LB: Fees are a real drag on investment returns. Vic, Do you think investors should invest with active managers that charge substantial fees?

VH: Fees has gotten a tremendous amount of study in academia and from practitioners. And the overwhelming empirical evidence is that active mutual fund managers underperform index funds on average. And we even have this concept known as Sharpe’s arithmetic, that says that if you take all active managers and put them all together into a portfolio, that that portfolio would be the market portfolio. And so therefore, the return of all active managers combined would equal the return of the market portfolio, less the fees that they charge.

What’s even potentially more detrimental than just the fees is that when you’re choosing active managers. “Well, if somebody has a good track record, I’m going to invest in them.” And when somebody starts to have a bad track record, they pull the money out. So, this return chasing winds up resulting in investors getting even worse returns then the returns of the funds themselves, this divergence between investor returns versus fund returns. Investors can be doing much worse because they come in and go out at the wrong time in general.

The Cathie Woods Ark ETF is the poster child for this. Since she started back in 2014, the ETF that she runs might now be up 50%, but investors have lost billions of dollars because they got in after it had done well and now it’s down 70 or 80%.

When we pay more for something, we expect that we’re getting something better, and we normally do. A Bentley is a lot more expensive than a Chevy, and sure enough, Bentley is just a better car than a $30,000 Chevy, but investment fees are not really like that.

LB: Next question for Vic: Most wealth managers and mutual funds charge investors around 1 percent, but you only charge 12 basis points. How can you charge clients such a small fee?

VH: 12 basis points, we think it’s the appropriate level to charge for managing a diversified portfolio of assets in a sensible way. We use technology to deliver this effectively. What makes fees high is when you need to hire so-called experts to manage individual stock portfolios. Also in the wealth management business, there’s a lot of concierge services so it just winds up being a lot more expensive.

To the extent that people can unbundle the services that they need from actual investment management and portfolio management, they’re better off.

LB: Vic, you mentioned that you use a dynamic asset allocation model so that if interest rates go up by 1% and equities are unchanged that you buy more bonds and sell equities. Tell us about Elm’s model and your implementation of it.

VH: We think that markets are very efficient and so we don’t believe in individual stock picking, but we do think that it makes sense to change your asset allocation over time as interest rates and equity market risk premium change. And that is not inconsistent with the belief in efficient markets, that interest rates do change is not some market inefficiency. And the same goes with equity market risk premium, that stocks can sometimes offer higher or lower long-term expected returns, is something that makes a lot of sense. The world changes, investors are different than each other and levels of risk aversion change over time. Investors who have flexibility should change their asset allocation over time and that will generate better risk adjusted returns. The way that we do it in practice is really simple.

For equity markets, we use the cyclically adjusted earnings yield as an estimate of the long-term real return that we can expect to earn on equities. And we compare that to the safe asset real return, which is the yield on TIPS, inflation protected bonds issued by the US Treasury. And that difference between TIPS yield and the earnings yield of the broad equity markets is our estimate of the risk premium offered by each big equity market in the world.

We also make an adjustment for the changing degree of riskiness of each of these big equity markets. We use a one-year moving average momentum metric to manage the risk of the portfolio. So, in late 2021, we reduced allocations to equities by quite a bit because equities became more risky, interest rates were going up, equities had negative momentum, market risk was higher. And we reduced exposures then which turned out to be a reasonable thing to do. It’s all transparent rules based, which allows us to charge really low fees. Investors know what to expect because they know what the rules are that we’re using. And we also do tax harvesting and we pay a lot of attention to the ETFs that we use to keep costs down. The average expense ratio of all the ETFs we use tends to be seven or eight basis points.

LB: Myron, do you think passive investors should rebalance their portfolios over time?

MS: A passive investment or an index fund is really an active investment. If risks change, then staying exactly at a benchmark and not trying to adjust your risks is not the best investment strategy. Because our objective is to maximize our wealth subject to risk constraints. The investor doesn’t just want to buy and hold, the investor wants to increase wealth.

LB: You recommend focusing on compounded returns and not average returns. What does that mean and what is its relevance to passive investing?

MS: The index fund or a passive investment portfolio is a starting point. It is a static one period allocation. And every investor wants to increase their compound return. And when we move from a one period average return model to a compound return model, then we have to take account of risk. Risk is a very important component of the growth of your portfolio.

The compound return is less than the average return because of volatility.

LB: Let me give an example. Let’s say you make a positive return of 100% in the first period and lose 100% in the second period. You start with a 100, you have 200 after the first period, and zero at the end of the second period. In the average return is zero return which is the average of plus 100 and negative 100, but the reality is your bust.

MS: Volatility reduces compound return for every level of risk. If one is able to do dynamic asset allocation and keep risk at target that will increase your compound return. That’s what I’ve called, time diversification. And I think time diversification is more important than cross-sectional diversification.

LB: So let me simplify for our audience what you are saying. When most financial advisors speak about the benefits of diversification, they are talking about asset diversification by making different investments: US stocks, foreign stocks, US bonds, foreign bonds, real estate, hedge funds, whatever. And it is true that some risks can be diversified, but all of them are invested at the same time. So, if there is some extraordinary event like a pandemic, all risky assets will fall in value simultaneously because the pandemic undermines the value of nearly everything from an office building in Tokyo to a restaurant in Mumbai.

Myron, you have been a big advocate of the benefits of time diversification. And what you mean by that is that you want to take similar scaled risks for each time period.

If you want to save for your retirement in 25 years, you should take similar amounts of risk for each of those 25 years, so that you can diversify the risk from any one particularly bad period. You do not want to lose most of your money in one catastrophic risky period.

MS: What’s really important are the tails that’s suffering the big losses or missing the big gains. So, risk is really the tails. It’s trying to achieve larger great returns, or it’s trying to avoid great losses. And so, the tails are everything.

And unfortunately, in life, the normal distribution or the idea of mean variance doesn’t include the fact that distributions are really changing all the time, or that risk is changing, and risk management is very important.

It also assumes distributions are normal, but it doesn’t assume that the distributions might have fatter tails at times or might be skewed and are changing all the time. And so, that has to be taken into account in any dynamic risk management strategy that will enhance compound returns. The average doesn’t take account of volatility.

LB: Let me repeat what you are saying. If you are investing for the long run to maximize your wealth, you need to avoid big losses and you need to participate in the big gains. This is where all the major price action comes from.

The second concept is that the level of risk in the market varies each day, so that means you should change your portfolio composition to keep your risk constant. To get time diversification, you need to take around the same amount of risk each period, so you need to adjust your portfolio based on tomorrow’s expected risk.

Myron has been a big advocate of benefitting from time diversification. Vic, how do you think about its application to the asset allocation decision?

VH: It’s a really big contribution that he’s made to focus on time diversification.

Time diversification has a lot to do with maximizing risk adjusted return over time. And we’re believers in the idea of time diversification. We use a risk metric to change our asset allocation, so when the markets become riskier, we reduce exposure and try to keep a more even amount of variability over time, which is exactly what Myron is a proponent of. It’s spot on.

LB: Vic, I want to contrast your dynamic investment portfolio approach relative to what other investment managers are doing. The most common method is something called a 60/40 portfolio allocation between stocks and bonds. This is a product offered by money managers where they put 60% of your portfolio in stocks and 40% in bonds, and then monthly or quarterly, they readjust the portfolios when it’s out of whack. What do you think of that 60/40 strategy?

VH: The one thing it really has going for it is simplicity. The 60/40 portfolio is going to make sense every once in a while when the expected return and risk of stocks and bonds is approximately such as to make sense of a 60/40 allocation for you given your degree of risk aversion.

The better thing to do is make your portfolio be consistent with the expected return and the risk that the market is offering for risky assets, combined with your own personal level of risk aversion, and let that change in a systematic way over time, keeping an eye on fees and taxes.

LB: Myron, what do you think of the 60/40 portfolio recommendation?

MS: People say 60% of your assets should be in equity, 40% in bonds, which I guess is a level of average risk. The problem that I see with a 60/40 strategy is essentially that it doesn’t tell you how to be dynamic. It doesn’t tell you how to adjust.

It reminds me, my first wife who always wanted us to have cushions on our couches. And I said, “Okay, we have cushions on the couch.” But I tried to sit on the couch to use the cushion. No, I couldn’t sit on the couch to use the cushion. So I ask, “What good is the cushion? If we have a cushion and we have a reserve, how do we use the reserve?” And passive management is using the reserve.

Why should I just have the cushion all the time without ever sitting on the couch? And that’s a really important problem. So, there’s myriad issues with that 60/40 strategy in that regard.

LB: Myron, in our house my wife has five pillows on my side of the bed, and I don’t see the point of that either. Let me apply the cushion metaphor to the 60/40 portfolio allocation. Having bonds is like having a reserve to buy stocks after equities fall in price, but we always keep the cash in reserve and never use any more than the allocated extra buying power.

Andre Schleifer has written papers that wealth advisors are value add because they encourage individuals to invest in the stock market, And that otherwise, investors would be too cautious and would hold their money in cash and earn a lower long-term return because of their risk aversion.

Vic, what do you think of the benefit of a wealth advisor that charges 1% that encourages those individuals to invest in equities?

VH: I think the general idea is correct. Vanguard has coined the term ‘Advisor Alpha’ to quantify the idea that having a human advisor between you and your investment decisions can really result in much better portfolio performance over time by getting the asset allocation more correct and from stopping you from doing things. 100 basis points is just way too much for that. Maybe 10 or 12 basis points.

LB: Myron, one of the things I don’t understand is why there’s such a variation in investment management recommendations to the public. Some people encourage using wealth managers, some people encourage using active funds, some people encourage use of private equity. Why are there such different investment recommendations that are often contradictory?

MS: There’s a tremendous amount of data mining. We look at the past. And you can educate people, but if you haven’t experienced something, you completely forget it. I think experience is a great teacher and it’s one of the great things about life, is that all our lives are inductive. We look at the past data and we build models from the past data. So induction or data mining is pernicious. People look at the past, what has worked, that builds their intuition.

If you have theory, then you can add to theory by looking at experience. That’s terrific – but a lot of people take their experience and then they ignore theory.

When I first learned to golf, as Victor knows, I read 150 books on golf, I figured out that I was going to be a tremendous expert because I knew from the theory of how to play golf, how good I would be. And Larry, you know my golf game.

LB: Yeah, I know your game. It isn’t pretty.

MS: The problem is that I got on the course and even though I knew all the theory, my game was so bad relative to theory.

We data mine, we take a subset of reality, and we extrapolate from that. All the information that investors use or in which they think they can make money themselves are always subject to destruction because as you run through time, we find that there’s errors in the model. And as people find errors in the model, they reverse engineer the errors in people’s models and they game against them.

They figure out ways to game against it. The system is dynamic. Everything changes.

LB: These past two years have seen some ridiculous investment behavior with the SPAC craze and the surge in the valuation of meme stocks like GameStop. Do you incorporate seemingly misvalued assets in your portfolio management?

VH: Gene Fama is the biggest proponent of efficient markets. I think that he makes a really great point, there’s just all this stuff that looks totally inefficient and crazy, but it’s really hard to make money from it. That’s the test. I mean, it’s not a test to be able to say this looks ridiculous. The test is, is it easy to make money from it? And I just think that it’s really, really hard to make money from market inefficiency.

Markets are efficient enough that I don’t want to try to benefit from their limited inefficiencies, and at Elm we take it that markets are pretty efficient.

LB: Myron, you won the Nobel Prize for your work with Fischer Black that created the Black-Scholes options pricing model. Some critics complain that the assumptions in your model do not match the real world. One example is the assumption that stock returns have constant volatility over time.

MS: When Fischer and I initially built the technology, we used a theory to replicate an option by a combination of a bond and a risky asset. We also had the idea of changing volatilities but we could not get a closed form solution. In other words, a simple formula you can put in Excel.

Fischer and I decided, “Let’s make some assumptions, okay? Let’s assume the risk free rate is constant. Let’s assume the volatility is constant. Let’s assume that there’s no dividends.” Then we could get a closed-form solution.

So that’s a model. And a model is an incomplete description of reality. Basically, the model has errors to it. That’s by definition what a model is because every model is an incomplete description of reality, even though the theory was exact.

LB: Let’s talk taxes. Taxes are drag on the portfolio performance. Vic, how can investors be tax efficient?

VH: I think that taxes are a first order consideration in how you invest. You want to look at every investment that you’re making on an after-tax basis.

Equities are very tax efficient. You tend to get a lot of deferral, and you get long-term capital gains treatment. Then there’s tax loss harvesting that feels like a low-hanging fruit that most people should avail themselves of.

And individuals wind up in a situation where they have some small set of investments that are very appreciated. They got lucky and they’re up 10x or and they represent 50 or 70% of somebody’s portfolio. In those cases, you have to make decisions about, do I realize some gains, pay some tax and get into a more diversified portfolio versus holding onto this highly appreciated asset with the idea that maybe someday I’ll leave it in my estate, and I’ll get a step-up basis if the step-up basis rules don’t change? Or I just defer the tax for as long as possible or maybe I’m in a high tax state and I plan to retire to Florida, and so I say I’m going to hold it for another five years and then when I move to Florida, I’ll realize the gain.

Having to put a price on the risk of having a less diversified portfolio, having more risk than you want. And what we’ve found is that for highly-appreciated assets that represent more than 50% of your total portfolio, it usually makes sense to pair those back and get more diversified – but, if you have something that represents 2% or 3% of your portfolio and is not having a big impact on your overall portfolio risk, you can leave it there and decide what to do with it in the future.

You might also decide to give it away in charitable giving and get the deduction on the market value and never have to pay that capital gain. Taxes are really, really important.

LB: Myron, when should we sell our winners and recognize income for tax purposes?

MS: The government is our partner. If I can make abnormal returns, then I can make 12% and the government’s going to take 6%. I’m better off paying the government 6% than making nothing. You have to be rational. Our object is to maximize our expected compound return after tax.

We have to be dynamic in our asset allocation to maximize our lifetime consumption, which includes not only our own consumption but the consumption of others.

A lot of investors incur taxes as they’re adjusting their portfolio because their circumstances changed.

LB: Let’s assume that you’re a wealthy taxpayer living in a high tax state at the 50% tax rate. If that taxpayer invests in a hedge fund with a 2% management fee and a 20% incentives fee. Under current tax law, the 2% management fee would not be tax deductible. Let’s assume they have a gross return before fees of 10%. The total fees are 3.6% and the taxes would be an additional 4.2%, so the investor only gets a 2.2% after-tax return.

Vic, what do you think of the after-tax economics for a hedge fund investment?

VH: I don’t think there’s anything for me to say, is there? I don’t think these vehicles make sense for highly-taxed, affluent US investors.

LB: Next question is on international diversification. Right now, we’ve had this period where US equities have done so well and we have people like Warren Buffett just telling people, “Put all your equity exposure into the S&P 500. That’s good enough.” Myron, What do you think about international diversification?

MS: Obviously, international diversification reduces idiosyncratic risk. We’re part of a global world, if you just hold assets in the S&P 500, then you are not as diversified.

The world is not only the United States or assets in the S&P 500. The world includes China, the world includes Japan, the world includes Europe. The world includes a tremendous amount of other investment opportunities and why preclude ourselves from adding them into the equilibrium portfolio?

There are benefits, obviously, through diversification and there’s myriad ways to achieve this diversification very inexpensively now. And so, investors should include that in their portfolio.

LB: Vic, in the 1990s we both worked in Salomon Brothers’ Tokyo Proprietary Trading Department. I was flabbergasted by how high the Price to Earnings ratios were in Japan at that time and how low the expected equity returns were available to investors. Americans had little exposure to the Japanese stock market, and almost all Japanese equities were then owned by Japanese individuals.

And I said to myself at the time, “It’s a big world out there. I don’t need to own these Japanese stocks. I’ll leave that for the Japanese.” How has that experience shaped your views on international diversification?

VH: When I designed Elm Wealth, the Japanese experience was in my thinking – and not only does the Japanese experience make me want to be eyes open about what I’m investing in, rather than just purely market cap weighted, I wanted to be forward looking.

Different big markets can offer very meager or sometimes very attractive long-term expected returns, and we should be able to avail ourselves of everything that’s happening in the world. I’m a strong believer in international diversification.

That doesn’t mean that you always want to have a lot of non-US equities. It just means that you want to be looking at the whole world to build your portfolio and not just invest in my home market because it’s my home market.

LB: Ibbotson analyzed 120 years of financial returns for stocks and bonds. Myron, what do you think of the past 120 years as a predictor for the future and whether stocks will continue to outperform other assets?

MS: We think of the return on equities as having a premium over the return on safe assets. I expect to earn a higher return on investing in risky assets that are correlated with my future consumption needs. And that’s basic theory.

Expectations, however, are different from realizations. This is an interesting argument in finance that if I have a long horizon, I should be in equities and not in cash or bonds. Okay? That’s the argument. By investing in equities, I’m virtually certain to outperform investing in bonds or cash over this long horizon period. And then you say, “Virtually certain? Wow, that’s great.” If I can invest in stock over this 20-year period, there’s some chance that if I keep my money in stocks, I could lose 60% or 70% of my money. So, if someone is going to make it virtually certain, it’s not the mean that counts, it’s the distribution around the mean that counts. What’s the shortfall going to be? That’s what you want to ensure against in life. It’s the shortfall. Not that I’m going to on average outperform someone. When is a shortfall going to occur? What am I going to do if the shortfall does occur? Can I stay in the game for 20 years? Those are important questions.

So, it means what risk you take and how you dynamically adjust your risk is a crucial aspect.

LB: Vic, how does the Ibbotson’s 120-year historical analysis shape your thinking about investing in equities for the long run?

VH: I would say very little for two reasons. First, 120 years is actually not that much data for trying to estimate a process that itself is moving around and where each year equities have 18% variability. 120 years is just not that long even if the world didn’t change over that period and we were just trying to estimate something like a coin flip out of it. The more important thing is that we need to look prospectively into the future.

If we’re going to buy a 10-year bond, we just need to look at the yield of that bond to know what return we should expect over the next 10 years from owning that bond. It’s called yield to maturity. We don’t care what was the return on bonds over the last 100 years because we just care about what its yield is today, not what the return was.

And the same goes for equities. Like the fact that equities were trading at a P/E of 10 at many times in the first half of the 20th century means that their returns were going to be pretty high for the next 50 years. We need to look at what’s the P/E today. We need to be looking into the future, looking at cash flows, looking at promised yields on bonds to make our asset allocation decisions. We should make our decisions with what the markets are offering us today, not what the returns have been in the past. We need to be looking to the future, not in the rearview mirror to do our asset allocation. And that’s why our asset allocation should change over time, because what the market offers is changing over time.

LB: How do you determine how to allocate between stocks, bonds, and other assets in your Elm portfolio model?

VH: The ideal portfolio is an individual specific choice depending on your degree of risk tolerance for a given amount of expected excess return offered by risky assets. You’re going to want to have a different amount of exposure than somebody else with a different degree of risk aversion. At Elm, we have a baseline product that we offer to people. And if that doesn’t really match their risk tolerance, then Elm can make their total portfolio less risky, like having more fixed income. Also, we do customized portfolios for people to their level of risk aversion.

We want everything that we put into people’s portfolios to be low-cost, diversified, and big asset classes where we can have some idea of measuring the expected returns in the future. We tend to stay away from things that are not liquid.

We recognize that people will be attracted to other kinds of investments. And we just accept that that’s not going to be part of what we’re doing for them, and they need to do that on the side.

LB: Vic, what assets are the building blocks in portfolio design, and how do you implement that strategy for your Elm clients?

VH: We have a really simple offering, for US investors, we open an account at Fidelity or Schwab and we manage their account for them. They can put money in, take money out whenever they want, they get statements directly from Fidelity or the other brokers – it’s their account and it’s in their name, and anytime they want to remove us, that’s it, they just remove us and everything stays the same, there’s no realizations. We rebalance their portfolios on a weekly basis, moving towards our ever-changing targets, where our targets are evolving with changes in the expected return and riskiness of about 10 major asset classes.

LB: Tell us about some of the free tools that you have on your website to help investors figure out their own risk tolerance and other key ingredients to portfolio design?

VH: We have a bunch of interactive tools on our website, elmwealth.com. We have apps that can give you the historical returns on a daily basis of our different strategies that you can download and analyze. We have historical asset allocation that shows our different strategies over time.

Our most popular app on our website is a coin-flipping game where you can flip a coin which is biased 60/40 and see how you manage the risk of that over time or over a number of flips. And that’s hugely popular. Sometimes we get 100 playing that in a day. And that’s really very educational for people to just get a sense for what is randomness and what is it like to have an edge of 60/40 and how do I manage something like that over time.

We also have some tools that help with tax decisions like we were talking about earlier. If you have an appreciated asset and you’re trying to figure out what’s the optimal amount to reduce and pay taxes on today, you can put in expectations of future tax rates and come to useful answers.

And a lifetime consumption and portfolio choice tool which helps people to think about wealth and longevity and optimal investment and spending policies. It allows people to make better decisions about how much risk to take in their portfolios and what kind of spending policy makes sense.

LB: What are you optimistic about the field of finance?

MS: If I just got out of university at this moment, I would go into finance again. Finance is uncertainty. Uncertainty is the cornerstone of all our lives. It’s the cornerstone of everything we do, and understanding uncertainty, or how to think about uncertainty, is just unbelievably fascinating. It’s been fascinating for philosophers.

I’m so excited about uncertainty and how finance adds to it. The greatest investment you can do is keep educating your brain, keep building your human capital and try to preserve it. Eating the correct way, living life the correct way, loving the correct way, physical exercise.

And then types of investment are always changing. We’re always learning about how to make better investments, and that’s what’s exciting. If the world was static, I’d be bored. If the world is dynamic, I enjoy it. And the information set is so large, it allows us to keep learning and keep growing, because there’s so much learning that we still have ahead.

LB: Myron, what is unusual about your optimism is that it runs counter to risk aversion in finance theory. Normally, uncertainty makes us scared. Uncertainty in asset returns encourages us to hold more cash and fewer risky assets. Uncertainty is viewed as a negative, but you just said that uncertainty was a beautiful thing.

This reminds me of an episode of the TV show The Twilight Zone. Here’s the plot of the relevant show.

A guy dies. He wakes up wearing a tuxedo in a casino. He is thrilled because he loves casinos. He walks over to the roulette wheel and bets on red. It’s red and he wins. Then, he bets on 12. It’s 12. So, he moves away from the roulette wheel a winner and heads over to the bar where a pretty girl is seated. He orders a drink, and he makes a move on the girl, and he gets the girl.

This goes on day after day. He sees the manager. “Hey pit boss, do you have a second? I want to talk to you.” And he says, “Sure, what’s up?”

“Listen, is it possible that you can change things around here, so I don’t win every bet. If I bet on red, how about it comes up black every so often? I bet on 12, it comes up 14. I go to the bar, I try to pick up the girl, I’m a little fresh. She throws the drink in my face. Okay? How about a little bit of that? Winning every time, it’s no good. Can you throw me a bone.” This is how I think heaven should be. And the pit boss says, “who told you this was heaven?”

MS: That’s correct. This is a story I always thought about.

LB: Vic, what are you optimistic about?

VH: People have been making better financial decisions over time. If you go back to the 1950s or 1960s, there’s a Fed study that found that the median number of stocks that were held in an individual’s brokerage account was two. Back then, people just didn’t get diversification at all.

Today, the use of broadly-diversified index funds has become so prevalent among individual investors. We’re just moving in the right direction with regard to people making better financial decisions for themselves. Now, there’s bumps along the way – the whole meme stock thing in 2020 and 2021 was disheartening for me – but overall, we’re on a great trajectory for people making better and better financial decisions, people being more disciplined in what they’re doing, and new technologies that are helping people to make better decisions with lower fees. What we do at Elm, we couldn’t have done 20 years ago because of technology, because of the low-cost broad index funds that are covering all major asset classes. I’m optimistic on better financial outcomes for more people as we go through time.

LB: Thanks to Vic and Myron for joining us today. If the ideas we just discussed resonate with you, visit elmwealth.com where you can find a lot of relevant research and tools, and where you can get in touch with Vic and his team for a deeper dive.
Read More

A Missing Piece of the SBF Puzzle

November 28, 2022

Investing 101

A Missing Piece of the SBF Puzzle

By Victor Haghani and James White 1

There’s much that’s being written about Sam Bankman-Fried (SBF) and the choices he made. We think there’s one particular aspect of his thinking and actions that has received less attention than it deserves, and perhaps explains better than anything else the arc of his narrative.2

In a range of interviews and Twitter threads (see links and excerpts below), SBF explained that he approached financial decisions with little or no aversion to risk. That’s a valid personal choice, but it’s highly unusual. In our own experience, we’ve never met anyone who made important financial decisions consistent with being anywhere in the ballpark of zero risk aversion.

To see why, it’s helpful to take a look at where risk-aversion comes from. It arises from the fact that most people derive less and less incremental satisfaction from progressive increases in wealth – or, as economists like to say: most people exhibit diminishing marginal utility of wealth. This naturally leads to risk aversion because a loss hurts more than the equivalent gain feels good. The classic Theory of Choice Under Uncertainty recommends making decisions that maximize Expected Utility, which is the probability-weighted average of all possible utility outcomes.

SBF explained on multiple occasions that his level of risk-aversion was so low that he didn’t need to think about maximizing Expected Utility, but could instead just make his decisions based on maximizing the Expected Value of his wealth directly. So what does this mean in practice? Let’s say you find an investment which has a 1% chance of a 10,000x payoff, but a 99% chance of winding up worth zero. It has a very high expected return, but it’s also very risky.3 How much of your total wealth would you want to invest in it?4

There’s no right or wrong answer; it’s down to your own personal preferences. However, we think most affluent people would invest somewhere between 0.1% and 1% of their wealth in this investment, based on observing other risky choices such people make and surveys we’ve conducted (e.g. here). We suspect that range sounds reasonable to you.5

SBF on the other hand, making his decision strictly according to his stated preferences, would choose to invest 100% of his wealth in this investment, because it maximizes the Expected Value of his wealth. In one of his interviews, he did suggest that perhaps he wouldn’t go all the way to 100%, but that he’d still invest way, way more than the typical choice of 0.1% to 1%. However, in other interviews, he didn’t back off of the implications of maximizing Expected Value – as in, for example, his conversation with the economist Tyler Cowen (March 9, 2022).

Tyler Cowen (TC): Should a Benthamite6 be risk-neutral with regard to social welfare?

SBF: Yes, that I feel very strongly about.

TC: Ok, but let’s say there’s a game: 51% [chance] you double the earth out somewhere else, 49% it all disappears. And would you keep on playing that game, double or nothing?

SBF: Yeah…take the pure hypothetical… yeah.

TC: So then you keep on playing the game. What’s the chance we’re left with anything? Don’t I just St. Petersburg Paradox7 you into non-existence?

SBF: No, not necessarily – maybe [we’re] St. Petersburg paradox-ed [sic] into an enormously valuable existence. That’s the other option.

We’re all entitled to our own preferences, but our preferences have consequences – and there’s a lot of evidence, both philosophical and practical, that when SBF’s stated preferences encounter the real world, it results in almost surely going bust at some point, and pretty quickly for someone who knows their way around financial markets.

Such a person won’t have to search for special investment opportunities, like doing leveraged crypto arbitrage or founding a crypto exchange, to find risks that have positive expected value with low probabilities of big payoffs. For example, most would agree that the stock market has a positive expected return in excess of the risk-free rate. If out-of-the-money call options are fairly priced, repeatedly buying them would give the Expected Value maximizer ample opportunity to lose all their wealth in short order, offset by a vanishingly small chance of becoming the richest person in the world.

Below are a few examples of SBF laying out his decision-making framework.


Interview with Jacob Goldstein on What’s Your Problem, May 24, 2022:

Jacob Goldstein: I’m Jacob Goldstein and this is What’s Your Problem… My guest today is Sam Bankman-Fried and his problem is this: how do you save the world? Before we get to the interview, I just want to take a minute here and set up this one big idea, this really useful intellectual framework that drives almost everything Sam does. It’s called Expected Value.

SBF: I try to use it a lot because I think it sort of is the default correct way in some senses to calculate something. Like, if you’re just trying to do a generic calculation I think it’s usually the right thing to use… One of the sort of takeaways that often ends up coming from really thinking hard and critically about Expected Values is that you should go for it way more than is generally understood.

JG: Go big. You should really go really big, even if you probably will fail and wind up with zero.

SBF: That’s absolutely right… if you really do care linearly about money, if you really do think that getting that marginal you know dollars worth a lot – um, you know, even once you already have a lot of money, um then, it – it should lead you to think that… And so, anytime that, like, there is some non-zero and non-negligible chance of a really really good outcome are times when you’re gonna be incentivized more than seems natural probably to choose extreme outcomes.


Conversation with Rob Wiblin on the 80,000 Hours podcast, April 14, 2022:

SBF: Yeah. I think the way I saw it was like, let’s maximize EV: whatever is the highest net expected value thing is what we should do. As opposed to some super sublinear utility function, which is like, make sure that you continue on a moderately good path above all else, and then anything beyond that is gravy.

If you really are trying to maximize your impact, then at what point do you start hitting decreasing marginal returns? Well, in terms of doing good, there’s no such thing: more good is more good. It’s not like you did some good, so good doesn’t matter anymore…

That means that you should be pretty aggressive with what you’re doing, and really trying to hit home runs rather than just have some impact – because the upside is just absolutely enormous.


Better is Bigger, SBF Twitter Thread. 11:19 PM · Dec 10, 2020, @SBF_FTX

SBF: …What about a wackier bet? How about you only win 10% of the time, but if you do you get paid out 10,000x your bet size?

[So, if you have $100k,] Kelly suggests you only bet $10k: you’ll almost certainly lose. And if you kept doing this much more than $10k at a time, you’d probably blow out.

…this bet is great Expected Value; you win [more precisely, your Expected Value is] 1,000x your bet size.

…In many cases I think $10k is a reasonable bet. But I, personally, would do more. I’d probably do more like $50k.

Why? Because ultimately my utility function isn’t really logarithmic. It’s closer to linear.

…Kelly tells you that when the backdrop is trillions of dollars, there’s essentially no risk aversion on the scale of thousands or millions.

Put another way: if you’re maximizing EV(log(W+$1,000,000,000,000)) and W is much less than a trillion, this is very similar to just maximizing EV(W).

Does this mean you should be willing to accept a significant chance of failing to do much good sometimes?

Yes, it does. And that’s ok. If it was the right play in EV, sometimes you win and sometimes you lose.


It seems like SBF was essentially telling anyone who was listening that he’d either wind up with all the money in the world, which he’d then redistribute according to his Effective Altruist principles – or, much more likely, he’d die trying.


  1. This not is not an offer or solicitation to invest, nor should this be construed in any way as tax advice. Past returns are not indicative of future performance.
     

    Thank you to Rich Dewey, Antti Ilmanen, John Karubian and Jeff Rosenbluth for their help with this article. For a deeper dive, read this excellent article by Byrne Hobart at The Diff.

  2. This article is all about SBF applying his personal risk preferences with respect to his own money. We don’t know yet the facts of what actually happened, but nothing we discuss herein justifies any type of fraud or improper use of client or investor money.
  3. Its standard deviation, a conventional measure of risk used for more symmetric payoff outcomes, is about ten times bigger than the expected return of the investment. Hence, its Sharpe Ratio is just 0.1 – not particularly high – although we emphasize that these conventional metrics of risk, return and quality of investment are not designed for evaluating investments such as these.
  4. For the purpose of this thought experiment, assume that all of your wealth is financial wealth and that you are considering this as a one-time investment in isolation of other opportunities.
  5. But if it doesn’t, just consider what it would mean to bet, say, 20% of your wealth on such an opportunity multiple times. After twenty such investments, you’d have an 82% chance of having lost 99% of your wealth, and just an 18% chance of having won at least once. We think most people wouldn’t find that distribution of outcomes very attractive.
  6. A Benthamite Utilitarian. Sadly, there is much confusion between “utility” in the Benthamite Utilitarianism SBF has discussed a fair amount with respect to social-welfare choices, and “utility” as a tool for financial decision-making in classical economics and the Decision-Making Under Uncertainty context. These are really disparate ideas, but various issues with Benthamite Utility have (unfairly) tainted von Neumann-Morgenstern Expected Utility.
  7. From Wikipedia: “The St. Petersburg paradox, or St. Petersburg lottery, is a paradox involving the game of flipping a coin where the expected payoff of the theoretical lottery game approaches infinity but nevertheless seems to be worth only a very small amount to the participants.”
Read More

Who Wants Protection Like This?

November 15, 2022

Risk and Return

Who Wants Protection Like This?

By Victor Haghani and James White 1

The S&P 500 is down 15% over the past year,2 so you’d think this would have been a great time to own some protection on your portfolio. Unfortunately, that’s not how things have turned out in this bear market (at least not yet) and not for what is probably the most popular way of protecting a stock portfolio with options.

Your Money or Your Time? It Hurts to Lose Both

If you bought and rolled one-month put options on the S&P 500 to hedge an investment in that index, over the past year you’d have lost an extra 2% on top of the 15% loss from just holding the S&P 500 unhedged, not to mention the loss of your time spent managing the strategy. The Chicago Board Options Exchange (CBOE) makes this really easy to see, by publishing an index of daily returns on the S&P 500 hedged by buying and rolling 5% out-of-the-money put options. The index ticker is PPUT.3

A more apples-to-apples comparison would be the put-protected S&P 500 versus just owning less stocks. As the chart below shows, if you’d kept 65% of your portfolio in stocks and 35% in T-bills, roughly consistent with the average risk level of 100% stocks fully protected with put options, you’d have outperformed the hedged strategy by about 8% over the past year.

We’re not suggesting that when the stock market goes down, an options-protected portfolio will always do worse than both a 100% long portfolio or one with a reduced equity exposure. But, we are focusing on the experience of the past year to make the point that options are not a silver bullet and do not provide “for-sure protection”. Even in a bear market, a portfolio protected with options will not always do better than an unhedged portfolio, and can do a lot worse than one that protects itself by simply owning less equities.

Just Unlucky?

Yes and no.

Yes, the main reason for the poor relative performance of the put-protected portfolio over the past year is some unlucky timing of when the options were purchased and expired and the exact path the market took over the year.

And no, there’s also a sense in which this outcome wasn’t just a uniquely bad throw of the dice. There are several fundamentally unattractive features of protecting your portfolio with short term put options. One is the fact that it’s nearly impossible to know whether the options you’re buying are fairly-priced. Another is that the options strategy reduces desirable time diversification, which in turn reduces Sharpe Ratio4 relative to keeping a constant fraction in equities.5

Options and Time Diversification

Time diversification is reduced because the exposure to stocks from a put-hedged portfolio will vary quite dramatically over time – some periods of higher exposure and others of lower exposure mean there are fewer “important” days determining total periods returns, thus lower diversification. When the options are purchased, the effective market exposure will be around 65%. But, if the market drops and the options are deep in-the-money, the exposure will drop to close to nothing – or, if the market is well above the put option strike price the portfolio might have close to 100% exposure. We can see the reduced diversification through risk metrics too: a portfolio that has 100% in the stock market half the time and 30% in the market the other half the time will have volatility about 15% higher than that of a portfolio with a constant 65% exposure.6

So, even if the portfolio protected with put options has the same expected return as a portfolio that just owns less stocks, the risk of the protected portfolio will be higher and therefore the expected Sharpe Ratio will be lower.7 This is borne out by the long-term historical data for the PPUT index. From 1986 to present, the simpler portfolio of 65% in the S&P 500 and 35% in T-Bills had a 0.6% per annum higher return, lower risk, and a Sharpe Ratio which was 22% higher compared to the PPUT strategy.8 That 22% higher Sharpe Ratio actually represents nearly 50% more expected welfare, because not only would you have earned a 22% higher excess return for the same risk, but in addition, you should have wanted to have 22% more of the simpler stock/T-Bill portfolio than the put-protected portfolio strategy, since the quality of the former was higher. The result: twice as much improvement in your expected welfare.

When Do Options Help?

We recently co-authored an article with our friend Vladimir Ragulin, titled “Do Options Belong in the Portfolios of Individual Investors?” (Journal of Derivatives Spring 2022)

Our conclusion was that options are unlikely to be welfare-enhancing, let alone a panacea, for affluent individual investors with typical risk preferences in most circumstances. We know this is a pretty strong conclusion, given that options trading now rivals stock trading in daily volume. You’d think that must be a sign that a lot of people are benefiting themselves through all that voluntary trading. But on the other hand, a lot of money gets put down on tables from Vegas to Macau, and so perhaps we shouldn’t find it so shocking that there’s so much options trading even though it is a zero-sum game, or worse after transactions costs.


  1. This not is not an offer or solicitation to invest, nor should this be construed in any way as tax advice. Past returns are not indicative of future performance.
     

    Thanks to Vladimir Ragulin for his help with this article.

  2. To the end of October 2022.
  3. You can find the data on the CBOE website here.
  4. A simple measure of the quality of an investment, the Sharpe Ratio is the ratio of an asset’s return in excess of the risk-free rate divided by its standard deviation of returns.
  5. Assuming stock market returns are normally distributed and the options are fairly priced. This is a pretty strong result which will hold under a fair bit of deviation from these assumptions.
  6. The portfolio that spends half its time at 30% and half at 100% exposure to the market has volatility, σ, equal to √(.5 * (0.3 * σ)2 + .5 * (1.0 * σ)2), which is 14% higher than the 0.65 * σ for the portfolio with a constant 65% in the stock market.
  7. And, in case you’re wondering whether doing the opposite would be better, this loss of time diversification argument also weighs against the sometimes popular strategy of selling put options.
  8. The CBOE also publishes an index of returns from selling one-month 2% out-of-the-money put options (PUTY), which can be used to figure out how a portfolio protected with those put options would have done. The result since 1986 is pretty much the same as that for 5% out-of-the-money puts– lower return and lower Sharpe Ratio than a portfolio holding less stocks with about the same average exposure to the market.
Read More

A Sheep in Wolf’s Clothing

September 26, 2022

Investing 101

A Sheep in Wolf’s Clothing

By Victor Haghani and James White 1

It’s easy to overlook the fact that, in thinking about investment risk, we are implicitly making a choice about the benchmark against which risk is measured. It’s a convention, which we often take for granted, to use our local hard currency as the risk-less benchmark – but this choice, while very convenient, can also be misleading.

Let’s take the case where what you really care about is what you can buy with your wealth over your lifetime. You’re 50 years old and you can purchase an investment in your brokerage account, with a solid government guarantee that pays one dollar each year for the next 50 years and is adjusted for inflation in the exact goods and services you want to buy. That’s a “real annuity”; right now, you can buy it for $40, but the price is always fluctuating as supply and demand drives changes in real interest rates. In fact, one year ago, the price was way up at $65 – and so, had you bought it then, your brokerage statement would now be showing a loss of about 40%.2 Is this a risky investment?

The present value price of the real annuity fluctuates (wildly, in this example) while its long-term spending power remains constant. If you have a short horizon, it’s definitely risky – but, in terms of your personal spending that can be supported by buying the annuity and holding it, there’s no risk. Similarly, the spot prices of US inflation-protected bonds (TIPS) fluctuate a lot, but since they can be assembled into a portfolio similar to a long-term real annuity, they’re not very risky at all if you’re primarily concerned with supporting your long-term real spending.

What about the stock market? We know that stock markets fluctuate pretty significantly year-to-year, often varying from base-case returns by 20% or more. When we measure the long-term realized volatility of the stock market, we get estimates for the annualized standard deviation of returns in the 16% to 20% range for most broad markets in major currencies – but what if we thought about investing in the stock market from the perspective of our long-term real spending power, where real annuities and TIPS are essentially risk-free? How much would that change our assessment of stock market risk?

It’s hard to know the exact inflation-adjusted payments you should expect from a long-term stock market investment, but one estimate you could use is the Cyclically-Adjusted Earnings Yield, which suggests that your long-term spending which can be supported by the stock market is directly connected to average 10-year earnings.3 With this in mind, the chart below shows changes in US stock market earnings compared to price changes, decade by decade, for the past 140 years.4 What we see is that earnings have been about one-third as volatile as stock prices: 7% volatility for earnings and 20% for market prices. Note that this difference in perspective is quite distinct from having a short-term versus long-term investment horizon. When we compare changes in earnings versus changes in stock prices, in both cases we are looking at a relatively long ten-year horizon.

The recognition that stock prices are much more volatile than expected long-term earnings is not new. It was presented at least as early as 1980 by Robert Shiller in his seminal paper “Do Stock Prices Move Too Much to be Justified by Subsequent Changes in Dividends?”5 and is also at the heart of the long-debated “Equity Risk Premium Puzzle”. These days, most market scholars believe that stock market volatility arises mostly from changes in how much people value future earnings, rather than from changes in the expected future earnings themselves.6 Thus, if you’re focused on your long-term spending power and view a real annuity as your riskless benchmark, you will also find equities considerably less risky than their price volatility would suggest.


PS…

We should keep in mind the very severe limitations of using US experience in predicting the future. It is just one path that history could have taken, and in the above analysis it only provides us with fourteen observations of ten-year average earnings.7 Taking a long-term view, we must recognize that any given stock market is always in some danger of a total wipe-out in both price and earnings, as experienced by investors in Russian and Chinese stock markets in the 20th century. The best protections against this important, existential risk are global diversification, the avoidance of leverage, and the sensible sizing of your global stock market risk against your personal benchmark.


  1. This not is not an offer or solicitation to invest, nor should this be construed in any way as tax advice. Past returns are not indicative of future performance.
  2. This is because long-term real interest rates in the US have risen from about -1% a year ago to +1% today.
  3. A variety of corporate-growth models can produce the result that real equity returns will be centered around the earnings yield. One basic condition under which real returns will equal the earnings yield would be if company earnings can grow with inflation with all earnings paid out currently to shareholders. While these models are all caricatures of the real world in a variety of ways, they nonetheless provide a solid starting point for thinking about expected stock market returns and making sense of long-term historical data. For a more up-to-date evaluation of CAPE as a predictor of real equity returns, particularly assessed in non-US equity markets, see Keimling (2016). They conclude:
    “Existing research indicates that the cyclically adjusted Shiller CAPE has predicted long-term [real] returns in the S&P500 since 1881 fairly reliably for periods of more than 10 years.”

    Furthermore, the results of this paper indicate that this was also the case for 16 other international equity markets in the period from 1979 to 2015.

  4. Using data kindly provided by Professor Robert Shiller.
  5. For example, see Mehra and Prescott (1985) and Grossman and Shiller (1981).
  6. See John Cochrane’s 2010 AFA Presidential address, “Discount Rates” for an excellent, broad survey of the topic.
  7. The 95% confidence interval on the sample standard deviation measured from a sample size of 14 observations is about +/-40% of the sample standard deviation. If we believed that we were drawing from a stationary distribution (which we don’t), the 95% confidence interval on our estimates of the volatility of earnings and stock prices would be roughly 4% to 10%, and 12% to 28% respectively.
Read More

Bitcoin is Nothing Either Good or Bad, but Sizing Makes It So

July 7, 2022

Tax Matters

Bitcoin is Nothing Either Good or Bad, but Sizing Makes It So

By Victor Haghani and James White 1

“There is nothing either good or bad, but thinking makes it so.”
  – William Shakespeare, Hamlet Act II (1602).

If you had put $100,000 of your savings into Bitcoin at the end of 2020 and are still HODLring (crypto-nese for “holding on for dear life”) those coins today, you’d be down 20% on your investment given its drop in price from $25,000 to $20,000 (as of July 5th).

If going long was no good, how about going short? An investor who put $100,000 into a crypto-brokerage account to short $100,000 of Bitcoin, with no further trading, would have been wiped out just a few months later in mid-February 2021 when Bitcoin more than doubled. This kind of shorting is effectively a form of automatic doubling down, since as the value of the asset goes up, the value of the capital supporting it goes down, causing the short position to get bigger and bigger (quickly) relative to capital.2 So, while “buy and hold” is a real strategy, “sell and hold” isn’t generally workable in practice. Instead, the short position that most closely represents the opposite of the buy-and-hold long position can be thought of as funding an account with that same $100,000 and then establishing and managing the short position so that at all times the size of the short is equal to the account’s liquidation value.

How would this managed short have done since the end of 2020? While avoiding total wipeout, an investor shorting Bitcoin in this way would still have lost 50%. That’s right…over the past 18 months, you’d be down 20% from a 100% Bitcoin long position, and down 50% from the opposite managed short.3 Naturally, this seems strange and unfortunate! To help understand why it’s the case, we’re going to see if there’s some other constant proportion of capital – other than 100% long or 100% short – that the investor could have maintained, with regular rebalancing, which would have turned a profit.

We could simply search over all possible constant proportions to see which gave the best result over this period, but before we do that, let’s reason from first principles to figure out what we should expect to find. We tend to think about the quality of an investment by calculating its historical Sharpe Ratio, which takes the realized return of an asset in excess of the risk-free rate and divides it by the asset’s risk. Over this period, Bitcoin’s realized Sharpe Ratio, calculated from average daily returns, was +0.2. (for a deeper dive into how Bitcoin could have had a negative return of 20% but a positive Sharpe Ratio, see this footnote ➚)4 This suggests that Bitcoin was a fair, but not great, investment over this period – by comparison, broad equity markets have expected Sharpe Ratios of around 0.3. The optimal allocation to not-so-great, but very risky investments should be fairly small, so if there’s a capital proportion that’s profitable at all, we’d expect it to be fairly small too.

And indeed, this is exactly what we find, as indicated in the chart below.

The maximum profit of $3,000 was realized for an investor who kept a constant 25% of capital in Bitcoin over the whole period.5 In fact, any positive proportional investment up to about 50% would have resulted in a profit.6 However, you don’t make twice the profit from taking twice the exposure; in fact, at 50% exposure, the profit is zero, rather than two times $3,000. Note that this is not a buy-and-hold strategy; to maintain a constant proportion of capital in an asset, regular rebalancing is required.7

We can also see that there are not any constant proportions generating a profit from both the long and short sides. You can lose money from a wide range of symmetric longs and shorts, but the only way to make money was to have constant long exposure in the range 0% to 50%. Put another way, you have to both correctly judge the quality of the investment, and then size your investment consistently with that quality, and getting either materially wrong will generally result in losses.

There are a few things we can take away from this mini case study:

  1. These ideas are not specific to Bitcoin. We chose Bitcoin to illustrate them because they are easiest to see for highly volatile assets, and there are few assets that have been more volatile.
  2. We can’t say that an investment is good or bad without considering how we will manage its sizing over time: sizing is as important as evaluating an investment’s expected risk and return.
  3. While there are an infinite set of investment strategies involving a given asset,8 we can learn a lot from focusing on the simplest strategy: Constant Proportion investing.
  4. Among Constant Proportion investment strategies, there will be a range of investment sizes that will be profitable, with sizing above and below that rapidly becoming increasingly unprofitable. And the range of profitable sizes is strongly related to the quality of the investment.
  5. For a given investment, the realistic strategies which turn a profit are typically quite a small subset of the infinite number of total strategies to choose from.

  1. This not is not an offer or solicitation to invest, nor should this be construed in any way as tax advice. Past returns are not indicative of future performance.
  2. For example, if Bitcoin goes up 50%, the size of the position relative to the amount of capital supporting it would have moved from 1:1 to 3:1. Such an approach requires an unlimited amount of capital, which is an amount few real-world investors have access to. A leveraged long position requires the same sort of position management, since as the asset goes down, capital goes down faster, and the investor will need to sell some of the asset to keep the leverage ratio constant.
  3. You can read more about why this is the case in George Costanza At It Again: The Leveraged ETF Episode (2020). Throughout, we assume daily rebalancing, no transactions costs, no borrow fees and a zero risk-free rate. All data from Yahoo Finance.
  4. The reason the Sharpe Ratio was positive even though the Compound return over the period was negative is because Sharpe Ratio is computed using the Arithmetic average daily return of Bitcoin over the period, which for a risky asset will always be higher than the Compound, or Geometric average, return. Under some stylized assumptions, the difference between the Compound Return and the Arithmetic Return of a risky asset is equal to one-half of the variance of returns, a quantity known as “variance drag.”
     

    For Bitcoin over this period, the variance drag was about 30% per annum (30% = 0.5 * 0.772 )! The Arithmetic Return was not sufficiently positive to offset the 30% variance drag, and so the Geometric Return was negative, but it’s the Arithmetic Return that ultimately determines the quality of a regularly rebalanced investment opportunity. Another perspective is to say that Bitcoin’s realized Sharpe Ratio would be positive as long as it’s Compound Return was better than -30% pa, given its realized volatility.


    For a simple example of variance drag, consider an asset that goes up and down 10% each day for 10 days. The average daily return is 0, because it went up 10% an equal number of times as it went down 10% – but the Compound return will be negative because every time it goes up 10% and then down 10%, the asset winds up 1% lower than where it started, and so the Compound return will be negative. That’s the effect of volatility, and boy has Bitcoin been volatile!

  5. Readers familiar with the bet-sizing literature will recognize that the 25% proportion of capital corresponds to the Kelly Criterion, which over many bets– and here we have 557 daily bets– gives the highest end wealth. The Kelly calculation takes the Sharpe Ratio of 0.2 and divides it by the standard deviation of returns of about 80%, to arrive at a bet size of 0.2 / 0.8 = 25% .
  6. Note that we will not find cases where one can find long and short fractions that would both make money, i.e. the range of profitable proportional sizing will always start at 0 and either go positive or negative from there.
  7. Over this period, it didn’t make a material difference if you rebalance daily, weekly, or monthly. The Sharpe Ratios based on weekly and monthly returns were 0.21 and 0.23.
  8. For example, strategies involving buying or selling puts or calls, or other kinds of dynamic scaling strategies.
Read More